Payment API for Moving Money
Payment rails are the networks that move money between accounts. Modern Treasury connects you to ACH, RTP, FedNow, wire, push-to-card, checks, and stablecoins through one API.



Types of Payment Rails
Pick the rail that fits each payment. Every one runs on the same Payments API.
ACH
If you collect recurring payments from bank accounts, start with ACH debit.
RTP and FedNow
If funds must land on a weekend, start with RTP and FedNow.
Wire
If you need to send large-value, irrevocable transfers, start with wire.
Push-to-Card
If you only have the payee’s debit card, start with push-to-card.
Check
If checks are the industry standard or your customers prefer them, start with checks.
(Check deposits via RDC and lockbox coming soon)
Stablecoins
If you pay wallets or across borders around the clock, start with stablecoins.
ACH
Low-cost bank transfers for collections, payroll, direct deposits, recurring debits, and payouts that can wait a day. Same Day ACH included.
RTP and FedNow
Instant bank payments that settle in seconds, 24/7/365, with ACH fallback when a bank isn’t on the network.
Wire
Send large-value, irrevocable domestic transfers over Fedwire for loan funding and closings. Eligible customers can also send international USD wires over SWIFT.
Push-to-Card
Instant payouts to U.S. debit and prepaid cards when you don’t have the payee’s bank details.
Check
Send checks when your customers prefer them or checks are the industry standard. Check deposits via RDC and lockbox are coming soon.
Stablecoins
Send and receive USDG, USDC, and USDT, and convert between stablecoins and fiat.
One Payment Order Across Every Rail You Use
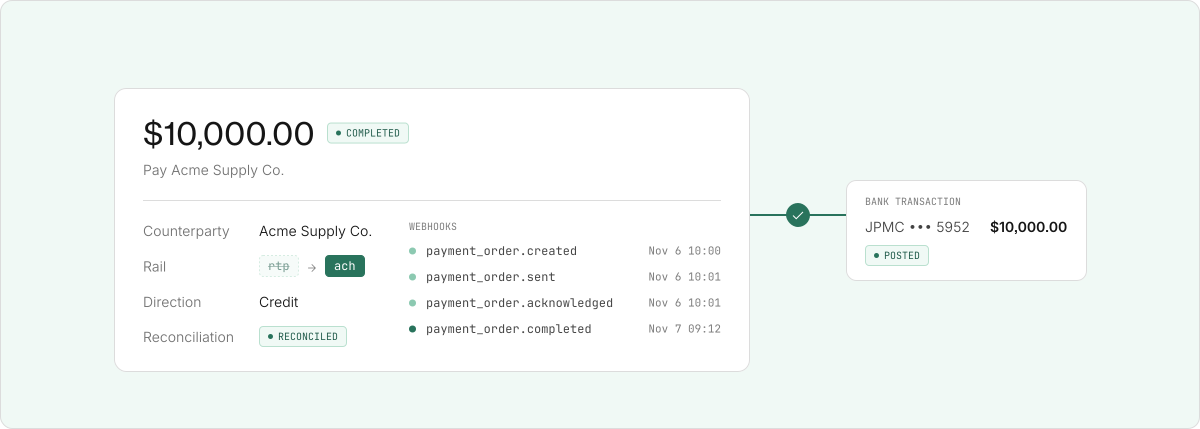
Pay Acme Supply Co.
- Counterparty
- Acme Supply Co.
- Rail
- rtpfalls back toach
- Direction
- Credit
- Reconciliation
- Reconciled
Webhooks
- payment_order.createdNov 6 10:00
- payment_order.sentNov 6 10:01
- payment_order.acknowledgedNov 6 10:01
- payment_order.completedNov 7 09:12
Create
Create a payment order with the amount, counterparty, and payment type.Send
Modern Treasury sends it on the rail you chose.Fall back
If the receiving bank can’t take RTP or FedNow, it can fall back to ACH.Track
Status updates and payment references reach you by webhook with payment failure handling.Reconcile
Each payment is matched to its bank transaction automatically.
Start Moving Money on the Rails Your Business Needs
Tell us what you send, what you collect, and how fast it needs to land.
- in payments processed
- $700B+
- uptime
- 99.99%
- across fiat and stablecoins
- 7 rails, 1 API
Customers
Code Once, Send Many Ways
- Industry
- Real estate
- Use case
- Loans & lending
“We have to support a multi-rail experience for our borrowers at scale, whether that be ACH, wire, check, or RTP. Modern Treasury allows us to code once and send a payment many ways.”
Jonathan Spinetto
Chief Operating Officer and Co-founder, NFTYDoor
- payments a month
- 16K+
- for Payments and Ledgers
- 1 API

- Industry
- Fintech
- Use case
- Embedded payroll
“We could write a code integration once, then flip traffic from one bank to another in the future with very limited developer work.”
Ian Zapolsky
Head of Product, Check
- to go live with Modern Treasury
- 8 weeks
- of development time saved
- 6 months
Frequently Asked Questions
Compare Payment Rails
| Payment attributes | ACH | RTP | FedNow | Wire | Push-to-Card | Check | Stablecoins |
|---|---|---|---|---|---|---|---|
| Settlement | Credits: 1 business day, or same day with Same Day ACH. Debits: 2–3 business days on MT | Seconds, 24/7 | Seconds, 24/7 | Domestic: same day if sent before close of business; next business day after. International USD: timing varies. | Seconds, 24/7 | Depends on mail time and when the payee deposits | Seconds to minutes, varies by chain |
| Availability | Business days | 24/7/365 | 24/7/365 | Banking hours | 24/7/365 | Business days; checks print in batches | 24/7/365 |
| Direction | Credit and debit (push and pull) | Credit push only; Request for Payment to collect | Credit push only | Credit push only | Send only | Credit push only; receive by lockbox or RDC | Push only |
| Finality | Reversible (returns up to 60 days) | Irrevocable | Irrevocable | Irrevocable | Reversible (stop payment, NSF, fraud returns) | Irreversible once confirmed | |
| Limit | High; same-day capped at $1M | Up to $10M | Up to $10M; each bank may set a lower limit | No network cap; limited by your bank | Set by program | No standard cap | Effectively uncapped |
| Cost | Cents per transaction | Low flat fee | Low flat fee | Highest per-payment cost of the bank rails; varies by provider. | Per transaction; above ACH | Low per check; high operational overhead | Network fee, varies by chain |
| Reach | All U.S. bank accounts | 1000+ financial institutions and growing | 1800+ financial institutions and growing | Domestic; outbound international USD to supported countries | All U.S. bank accounts | Any wallet on a supported chain | |
| Best for | High-volume recurring, payroll, low-cost debits | Instant B2B and disbursements | Instant payments, broad bank reach | High-value, time-critical, cross-border | Instant payouts to debit cards | Traditional B2B accounts payable, legacy industry workflows | Cross-border, 24/7 liquidity, thin corridors |
Sources: the spec tables on each Modern Treasury rail page (2026). Limits, cutoffs, and fees can vary by bank.