Send, Collect, and Reconcile ACH Payments
ACH is the U.S. bank-to-bank network for credits and debits. Modern Treasury’s ACH payments API lets you send, process, and collect ACH payments. Track every status, handle returns, and reconcile automatically.
Same Day ACH credit
Completes Mon
Next-day ACH credit
Completes Tue



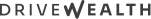
Collect and Pay Out Over ACH, With Every Dollar Tracked
Let Modern Treasury manage the infrastructure and nuances of ACH, from customer balances to returns and reconciliation. Leave the details to us.
Every Dollar Tracked to Its Owner
Give each customer a sub-account with its own account and routing number. Modern Treasury manages balances and matches incoming payments to the right customer automatically, so every dollar is tracked to its owner's balance. Every payment's status reaches you by webhook.
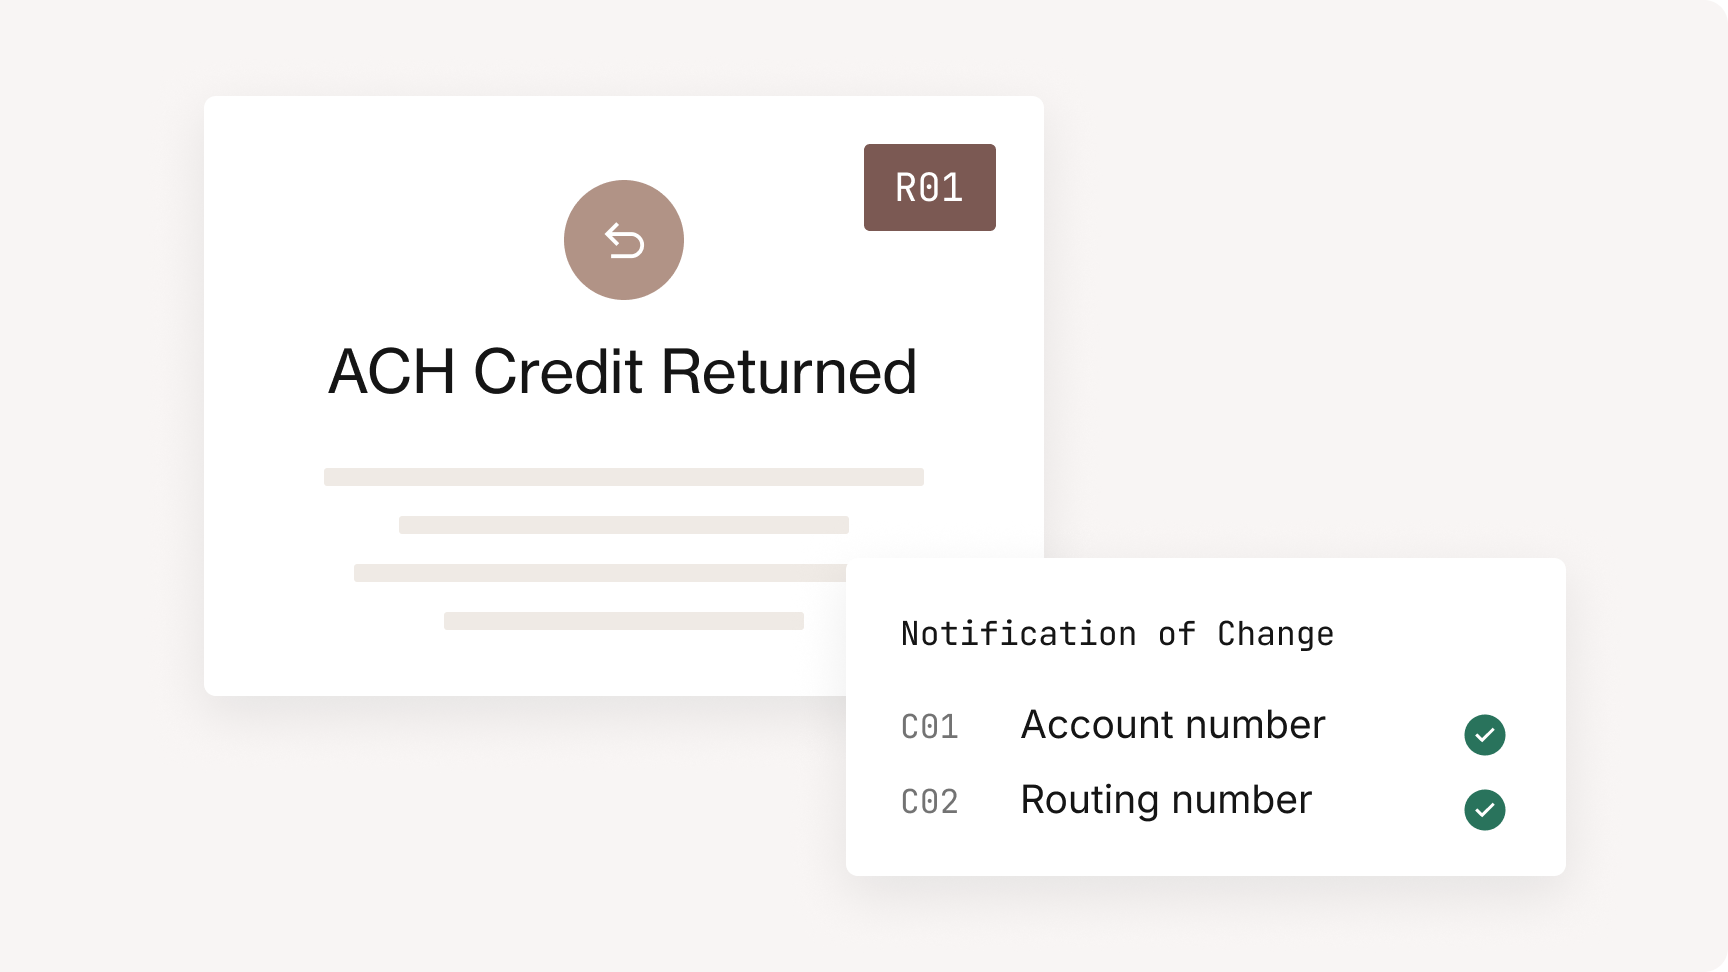
Know Where Every ACH Payment Stands
Track each payment order from approved to completed in the dashboard or by webhook. Expected payments reconcile incoming ACH automatically.
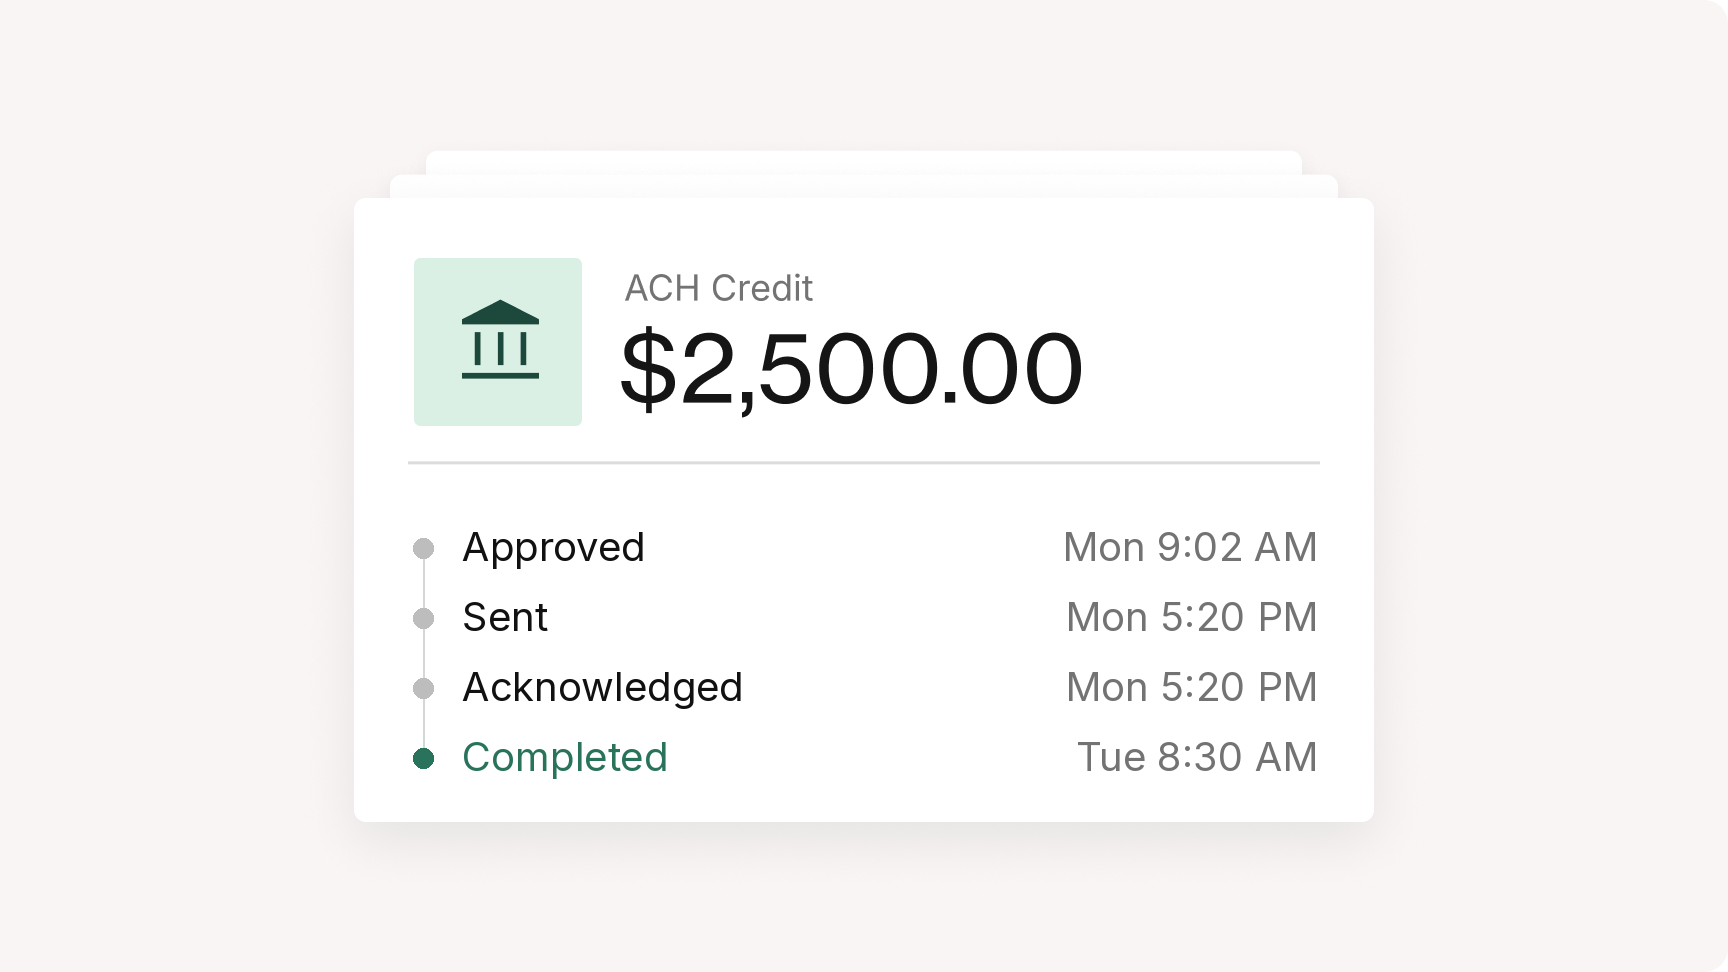
Start With ACH. Add Rails When You're Ready.
One API and one payment order cover every rail. Move a payment to Same Day ACH, RTP and FedNow, or wire by changing its type.
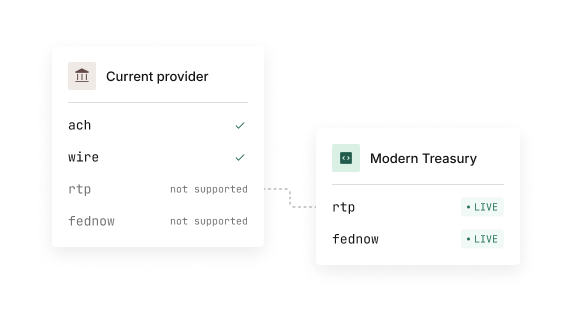
Add a Rail Your Current Provider Doesn’t Support
Keep your existing provider and add the payment rails you need through Modern Treasury’s API.
ACH at a Glance
ACH runs on payouts for credits and pay-ins for ACH collections.
| If you need to… | Best fit |
|---|---|
| Collect recurring debits and invoices | Next-day ACH |
| Run payroll and payouts that can wait a day | Next-day ACH |
| Get funds there the same banking day, before close of business | Same Day ACH |
| Land a payout in seconds, including nights and weekends | RTP / FedNow |
| Send large, irrevocable transfers such as loan funding | Wire |
| Send instant payouts to a recipient's debit card | Push-to-Card |
| Pay recipients with no bank details on file | Check |
| Send cross-border payouts settled in stablecoins | Stablecoins |
Need something else? See when Wire, Push-to-Card, Check, or Stablecoins fits better | |
| Same Day ACH | Next-day ACH | |
|---|---|---|
| Settlement | Credits: same day with Same Day ACH. Debits: 2–3 business days on MT. | Credits: 1 business day. Debits: 2–3 business days on MT. |
| Credit completes | Same banking day | 1 banking day |
| Per-payment limit | Same-day capped at $1M | High; set by the originating bank |
| Availability | Business days | Business days |
| Standard debit completion | 2–3 business days | 2–3 business days |
| Finality | Reversible (returns up to 60 days): 2 banking days for most codes; 60 calendar days for unauthorized consumer debits | Same as Same Day ACH |
| Direction | Credit and debit (push and pull) | Credit and debit (push and pull) |
| Cost profile | Cents per transaction; above next-day ACH | Cents per transaction; lowest-cost rail at volume |
| Reach | All U.S. bank accounts | All U.S. bank accounts |
Customers
Platforms Run on Modern Treasury

- Industry
- Real estate
- Use case
- Capital raises & distributions
“Sponsors come to us because they want to spend their time closing deals instead of chasing down accounts and wiring distributions by hand. Modern Treasury lets us move investor capital in and distributions back out, over ACH, RTP, FedNow, and wires, without building or maintaining that infrastructure ourselves, so we can keep our promise of a fixed timeline and fixed cost to every sponsor on our platform.”
Lucas Parelius
Co-Founder and CEO, GrowIt
- in equity under management
- $100M+
- SPVs formed, each with its own named payment account
- 100+
- Industry
- Fintech
- Use case
- Capital marketplace payments
“If I can sleep well at night knowing that the right amount of money was moved to the right parties at the right time, then I’m happy.”
Lukas Wagner
CFO, Pipe
- implementation time with Modern Treasury
- 2 weeks
- in annual savings by automating payment operations
- $100K+
- Industry
- Travel & recreation
- Use case
- Marketplace payouts
“The faster transit times have allowed us to store and move all funds through our master account, which has improved our relationship with our bank.”
Tyler Stillwater
Lead Backend Developer, Outdoorsy
- payout time, down from 3–5 days
- 24 hours
- to build the alpha integration
- 2 days
Send an ACH Payment With One API Call
{
  "type": "ach",
  "amount": 1000,
  "direction": "debit",
  "currency": "USD",
  "originating_account_id": "0f8e3719-3dfd-4613-9bbf-c0333781b59f",
  "receiving_account_id": "5acec2ef-987b-4260-aa97-b719eeb0a8d5"
}
201 · PAYMENT_ORDER
- status:
- "approved"
- type:
- "ach"
Start Sending or Receiving ACH Payments
Tell us about your ACH volume, your flows, and when you want to launch.
Frequently Asked Questions
Direct answers for teams running ACH.
Verify bank accounts to help reduce ACH returns. Modern Treasury doesn't enforce verification on its platform, but you must meet the Nacha and bank-partner requirements that apply to your debits and payouts. Verifying cuts returns. You can verify an external account three ways: instantly with Plaid; with two microdeposits under $1 that the account holder confirms within one to two days; or with a $0 ACH prenote that needs no action from them but takes time to complete. Each external account carries a verification status in the API and in webhooks.
Only in limited cases. Nacha allows a reversal for a duplicate payment, the wrong recipient, the wrong amount, a debit sent earlier than intended, or a credit sent later than intended. The reversal must reach the bank within 24 hours of finding the error and no later than five banking days after settlement, and you must tell the recipient. Modern Treasury creates the reversal from the original payment order and reports its status by webhook. Reversals aren't available at every bank; check with your Modern Treasury contact.
The SEC code tells the receiving bank how the payment was authorized. Modern Treasury sets PPD when the receiving account belongs to an individual and CCD when it belongs to a business. You can override it with the payment order's subtype, for example WEB for a debit authorized online. A wrong code can lead to a return, such as R05 for an unauthorized consumer debit sent with a corporate code.
Nacha sets return-rate limits. Going over can limit your access to bank partners and to the ACH network. Modern Treasury tracks your ACH return rate so you can act before you reach a limit. See the full list of ACH Return Codes.